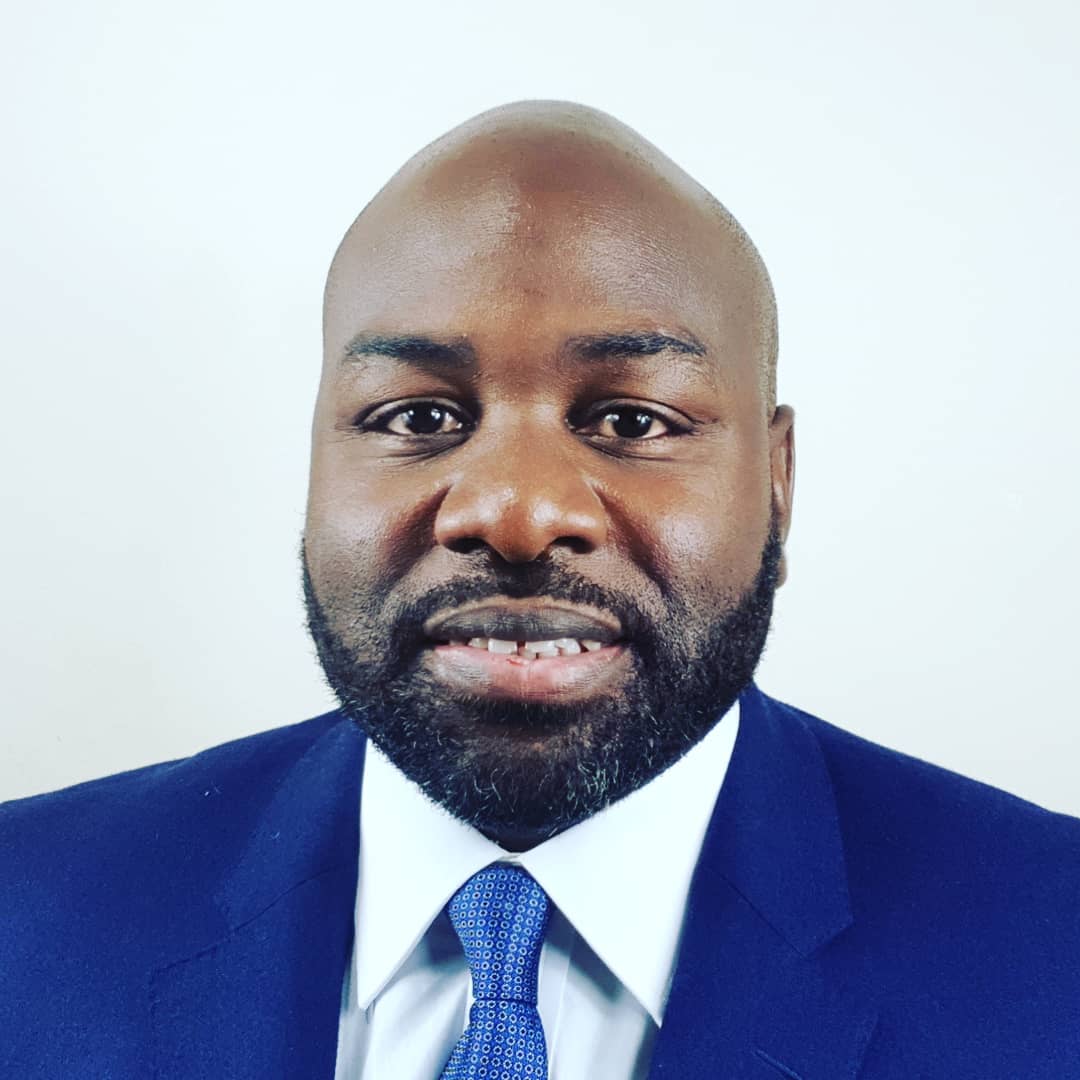
Anthony Anakwue
Anthony has over 18 years of experience in private equity, business strategy, entrepreneurship and management consultancy, of which the last 8 were spent supporting global firms wishing to expand into Africa. He combines a deep operational and entrepreneurial background with senior-level experience working alongside international private equity firms, and has made successful principal investments in early-stage ventures. He holds an MEng in Electronic Engineering from Brunel University London.
UK fintech down-rounds eased in Q1 2026, but bridge and extension capital remains meaningful, giving existing investors more leverage in constrained financings. Broad follow-on rights can fill the allocation needed by a new lead, while pay-to-play can shift protection and influence towards investors that fund the next round.
Sponsors often treat commercial operation as the finish line for refinancing risk. The cases from Bahrain to Chile show that COD removes construction risk, but it does not create the cash-flow headroom or legal flexibility a new lender needs.
Infrastructure sponsors often treat cyber as an operating risk managed through security controls, insurance and force majeure. The evidence from ports, pipelines, telecommunications and industrial companies shows a different problem: an asset can be excused from performing, or prudently shut down, while revenue falls and debt obligations continue. The central task is to test every plausible incident against contractual payments, insurance wording, reserve capacity and lender remedies.
A near-complete financing is not money in the bank, as DoDots discovered when its term sheet collapsed during the dot-com crash. Unify’s later pre-emptive offer shows the opposite position: founders with runway can assess an offer on its merits. The real task is to align verified cash, current evidence and one measurable next milestone.
Continuation funds are usually presented as a simple choice: take cash today or remain invested in a quality company for longer. Yet 80-90% of legacy LPs choose cash, according to the CFA Institute. The evidence suggests the issue is not necessarily whether the underlying companies are good or whether continuation funds perform worse. HEC Paris found little broad return difference by fund type or geography. The harder question is whether the transaction gives investors a genuinely tested price and fair new terms when the same manager sits on both sides of the sale. Research from the CFA Institute, NYPPEX, Berkeley Law and the 2025 game-theoretic work cited in the brief points to the same conclusion: optionality is not protection unless process, economics and governance withstand the standard of a third-party sale.
Companies can satisfy an exchange’s admission rules and still be dangerously unprepared for public ownership. Evidence from India, the United States and China shows that the damage usually begins when a technically eligible company meets investors who do not trust its price, profits or shareholder structure.
South-East Asian founders are often told that 1x non-participating preferred shares are founder-friendly. That can be true for one round, but it becomes misleading when earlier preferences remain in place, investors participate twice, or conversion rules only work at valuations the company may never reach.
UK seed benchmarks look precise until the outliers are removed, and early ARR often conceals more than it reveals. The companies that earn conviction show investors how one tightly defined customer can be found, converted, implemented and retained with less uncertainty each time.
Founders often treat a signed foreign investment agreement as the finish line, then discover that screening rules, bank checks, corporate procedures and payment documentation still control the wire. Cases from Cerebras to MTN Nigeria show that the last uncleared gate, not the signature, determines when capital becomes usable cash.
A solar plant in Rajasthan had a 25-year fixed-tariff contract and still lost 12-18% of its output to curtailment. The lesson is that renewable energy curtailment risk, capture prices and dispatch control now matter more to lenders than headline capacity or equipment cost.
GlobalWafers’ €4.35 billion pursuit of Siltronic shows how a regulator can defeat a transaction simply by running out the clock. The lesson is not that sensitive assets are unbuyable. Buyers keep pursuing them precisely because chips, ports, data and supply chains matter commercially and strategically. But Trieste, where a Maersk/HHLA transaction was screened and cleared, shows that clearance remains possible. The difference lies in the asset, the buyer’s ownership chain, the political setting, the likely remedies and, above all, whether the deal can survive the wait.
A strong track record can win an investment team’s enthusiasm and still lose an institutional allocation in operational due diligence. Abraaj’s collapse, a halted $140 million acquisition and the growing use of operational vetoes all point to the same lesson: institutional investors are not just assessing whether a manager can make money, but whether its systems can be trusted when something goes wrong.
Companies do not raise capital simply because demand is rising. They raise it when lenders and investors can see, test and trust how revenue becomes controllable cash.
From Toronto to Kochi, smart-city schemes have shown that working technology is not the same thing as an operating public service. The projects that scale treat data, budgets, authority and vendor exit as infrastructure questions, not IT details.
Sovereign wealth funds are often treated as one vast pool of patient capital. The evidence from Abu Dhabi, India, Nigeria and Saudi Arabia shows that mandate fit, governance and national value matter far more than a fund’s reported size.
Angola, Peru and South Africa show why special economic zone status and generous incentives do not automatically create export industries. Ghana and newer ASEAN models suggest that durable zones are operating ecosystems, not discounted parcels of land.
A founder-led business can look profitable on paper yet lose value when an investor discovers that customer trust, authority and family obligations live in one person’s head. The answer is not a prettier succession plan, but demonstrable transferability before the deal closes.
Development finance institutions do not fund impact claims in isolation. The projects that reach approval are those that turn an impact ambition into documented, risk-controlled and commercially credible evidence.
Governments can announce large manufacturing incentives, but the headline number says little about whether a factory can use the money during construction. Cases from China, India, the United States and Russia show that documentation and timing, not generosity, determine whether public support is bankable. Buffalo offers a separate warning: a large incentive can also produce disappointing economic returns, though that finding does not itself prove how factory cash flowed.
The usual mine valuation counts remaining reserves as value and closure as a discounted cost for later. Evidence from South Africa, Papua New Guinea, Brazil and major mining jurisdictions shows why that divide can be dangerously false: the cost of securing closure can constrain cash long before the mine stops producing.
In 2012, seven NHS trusts could not meet their PFI repayment obligations and required £1.5 billion in emergency funding. The cases that followed, from Australia, the United States and Iran, show why essential healthcare demand is not enough: payment security, operational readiness and credible public institutions determine whether a hospital PPP can survive.
A reputable overseas buyer and a large signed purchase order can still leave an exporter unable to fund production. The missing ingredient is not usually the order value but the legal, documentary and compliance chain that turns a commercial promise into collectable cash.
Data-centre lenders are discovering that a signed tenant lease cannot produce cash flow without deliverable power. Microsoft’s reported cancellations after US facility and power delays show how quickly projected rent can disappear. The projects that survive underwriting turn interconnection evidence into contractual milestones, rather than treating it as an engineering footnote.
A financing announcement can conceal the question that matters most: when, and under what conditions, can the company actually use the money? From Britishvolt’s milestone-gated grant to Byju’s lender enforcement and M-KOPA’s receivables finance, the evidence shows that every source of capital changes what a business owes, who controls key decisions and what the next funder will inherit.
Evidence from Ethiopia, Lebanon, Ecuador, Türkiye and India points to a stubborn flaw in women’s SME finance: borrower numbers can rise while usable capital remains scarce. The programmes that changed outcomes altered the lender’s rules, from collateral and guarantees to customer journeys and cash-flow assessment. For capital providers, the real test is whether those changes produce profitable portfolios after the cost of risk-sharing is included.
Businesses often compare funding by valuation or interest rate, then discover that the real price was hidden in collateral, covenants, currency risk or control rights. From BYJU’S to Sun King, the cases show that capital is a contract for future bad days, not merely a cash injection for good ones.
The usual story says informal African businesses need to become formal before serious investors can fund them. The evidence points elsewhere: the decisive question is whether a company controls the payment, asset, inventory or servicing loop well enough to turn activity into enforceable cash flow.
The family-office cliché is a patient billionaire writing early cheques into future unicorns. The evidence from Theranos, Sweden, Hong Kong, Saudi Arabia and pan-Africa tells a tougher story: durable family capital depends less on wealth or founder chemistry than on whether the investor has the expertise, governance rights, funding capacity and exit plan to own a risk properly.
The usual explanation for a failed raise is that a business has not met the right investor. The harder truth is that demand, revenue and growth can still leave a company with no cash flow a capital provider can safely underwrite.
Founders often see a large VC fund, a recent fund close or a pro-rata right and assume future capital is available. The evidence from Capiter, Copia, Byju’s, Zilingo and Northvolt shows that reserves become real only when a company remains a priority and the financing can attract agreement around price, governance and risk.
Seeking capital?
Your application is the first step into the GI Network capital process.