Watu closed a US$7 million debt facility with AHL Venture Partners on 10 September 2026 to fund working capital and loan-book growth without issuing equity. The deal is a useful signal for founders, but the underwriting threshold is high: verified repayment, collateral, portfolio controls and market-specific risk protection matter more than ambition.
- ·Watu’s US$7 million AHL Venture Partners facility closed on 10 September 2026 and did not require new equity issuance.
- ·Watu’s more than seven million originated loans since 2015 gave a lender evidence beyond a growth story.
- ·AHL’s working-capital product is priced at 12% to 14% interest with a two-to-five-year repayment period, according to its July 2025 product material.
- ·Debt accounted for 57% of African startup funding in Q1 2026, up from 24% in late 2025 and 12.5% in 2024.
- ·Nigeria’s Drive45 shows that a good operating record may still need a guarantee where currency and political risks concern lenders.
- ·Debt can fund repeatable assets, while equity still has a role where a business is testing an uncertain model or needs broader growth funding.
A $7 million test of what lenders will fund
On 10 September 2026, Watu, the Kenya-founded asset-financing fintech, closed a US$7 million debt facility with AHL Venture Partners. The money is for working capital and loan-book growth, without new equity issuance. That matters because Watu has originated more than seven million loans since its 2015 founding, financing assets including motorcycles and smartphones across multiple African markets and Latin America. The transaction is not proof that any fintech can replace equity with debt. It is evidence that a lender will fund a loan book when it can see repayment behaviour, recoverable assets and a long operating record.

Watu’s September 2026 facility shows how a long repayment record can turn asset finance into lender-ready debt. Photo: Sam Hidayat / Wikimedia Commons, CC BY-SA 4.0.
A debt facility is a committed lending arrangement. In this case, it gives Watu capital to expand lending without equity dilution, meaning founders and existing shareholders do not surrender further ownership. For companies that finance revenue-producing or recoverable assets, this is an important distinction. Equity funds uncertainty. Portfolio debt is designed to fund a process that has already become repeatable.
The part most people miss is that the facility is not a reward for being a fintech. It is a credit decision on a portfolio. Watu’s reported seven million-plus loans and its asset-backed model gave AHL a body of evidence on which to judge repayment and collections. A founder with a polished deck, early users or a partnership announcement does not yet have the same evidence.
What changed in 2026
African startups have not suddenly discovered debt. Peg Africa combined US$13.5 million of debt and Series B equity for solar asset finance in 2017. Watu itself secured a US$5 million receivables-financing facility from AHL in December 2022 for expansion in Uganda. Receivables are payments customers still owe a business.
The change is pace and visibility. Debt represented only 12.5% of African startup funding in 2024. By Q1 2026, debt had risen to 57% of funding while equity fell to 43%, according to the figures in the research brief. Debt’s share had been 24% in late 2025. Fintech remained the largest sector in H1 2026, while debt’s share continued to rise.
That shift does not mean debt is easy money or cheaper money. AHL’s published working-capital product describes interest of 12% to 14% and a tenor, meaning the time allowed for repayment, of two to five years. It also expects a proven track record, strong margins and receivables or other collateral. Collateral is an asset a lender can recover or claim if repayment fails.
Critically, the public information in this brief does not set out Watu’s exact interest rate, repayment period, security package, loan rules or market-by-market allocation. Nor does it specify whether every dollar will fund new originations, refinance existing obligations or cover particular operating markets. Founders should not treat AHL’s general product terms as Watu’s confirmed deal terms. Investors should not either.
Still, the direction is clear. The question for a lending fintech is becoming less "Can I raise debt?" and more "Can an outside lender verify how my portfolio performs under stress?"
The underwriting threshold, not the fundraising preference
Watu operates in Kenya, Uganda, Tanzania, Côte d’Ivoire, Ghana, Nigeria, the Democratic Republic of Congo, Rwanda, Sierra Leone and South Africa, as well as Latin America. Its scale across markets is unusual. It should therefore be read as a high-bar example, rather than a benchmark that a pre-seed lender can immediately copy.
For an early-stage Africa-focused fintech, an idea and deck alone are not what this kind of lender is funding. The evidence in this brief points instead to live lending activity, observable collections, a record of repayment and assets that can support the loan book. The most relevant traction is not simply user numbers. It is whether the company can show that loans are repaid predictably and that financed assets can be recovered where necessary.
This also clarifies a common category error around mobile money loans. The Watu transaction is not presented in the research as a mobile money loan product. Its significance is asset finance, backed by motorcycles and smartphones. A mobile payment channel, an app-based product and a secured asset-finance portfolio are not automatically the same credit proposition. For a lender, the key issue here is the ability to underwrite payments and assets, not the label attached to the digital channel.
How do lenders price risk without traditional collateral? The cases in this brief suggest they try not to rely on that question alone. Watu and Spiro give lenders physical assets. Drive45 added a guarantee. A credit guarantee is a commitment that helps protect a lender against specified losses. This is a more concrete route to lender confidence than asking a lender to accept a growth narrative in place of security.
Fintech operators should also take the ethical side seriously. A business that pursues rapid loan growth without disciplined collections and repayment controls may damage both customers and its future ability to borrow. The immediate financing benefit from fast origination is not the same as a durable, financeable loan book. This brief does not provide Watu’s arrears, write-offs, recovery rates or customer outcomes. Those are precisely the kinds of portfolio measures a serious debt process should surface.
For founders preparing over the next 12 months, the practical test is whether their collections data could withstand an external review today. If not, the answer is not necessarily to seek more equity immediately. It may be to build a cleaner record first: consistent loan-level data, clear asset records, repeatable collections controls, evidence of repayment, and reporting that distinguishes growth from losses.
For an adjacent lesson on why proof matters more than presentation, read what institutional investors look for in due diligence. Debt lenders and equity investors ask different questions, but both will test whether the reported operating story can be verified.
Kenya and East Africa: assets can carry the case
Watu’s facility is strongest as a signal for asset-finance businesses with an established record. Its December 2022 US$5 million receivables facility with AHL also matters. The September 2026 facility was not a first encounter between borrower and lender. It followed an earlier financing relationship and years of operating history.
Spiro offers a second, larger example from East African e-mobility. In late 2025, it secured a US$50 million debt facility from Afreximbank, Nithio and Africa Go Green Fund. Its electric fleets and battery-swap infrastructure provided physical assets that lenders could assess. In mid-2026, Spiro then raised US$215 million in equity.

Spiro combined asset-backed debt in late 2025 with equity in mid-2026, showing the two forms of capital can work together. Photo: Wolfgang Sauber / Wikimedia Commons, CC BY-SA 3.0.
That sequence is important. Debt and equity are not interchangeable pots of money. Spiro used debt for asset-backed expansion, then also raised equity. A company may need equity to fund new markets, technology, organisational capacity or risks that do not fit a lender’s repayment model. It may need debt once the assets and collections have become legible to a lender.
For investors, that creates a better question than whether a portfolio company is “debt ready”. Ask which part of the plan is ready. A fleet or asset pool with recoverable value may be fundable through debt. A new product, an untested customer group or a market entry may still require equity. The same discipline applies to how investors read a pitch deck: the funding request should match the evidence behind the use of proceeds.
Nigeria: operating quality may not be enough
Drive45’s September 2026 US$3 million direct debt facility in Nigeria provides the necessary caution. The asset-financing fleet operator, founded in 2021, had a strong operating record and no default history, according to the research brief. Yet the facility was supported by a Cascador/Morgan Stanley credit guarantee to address lender concerns around currency and political risk.
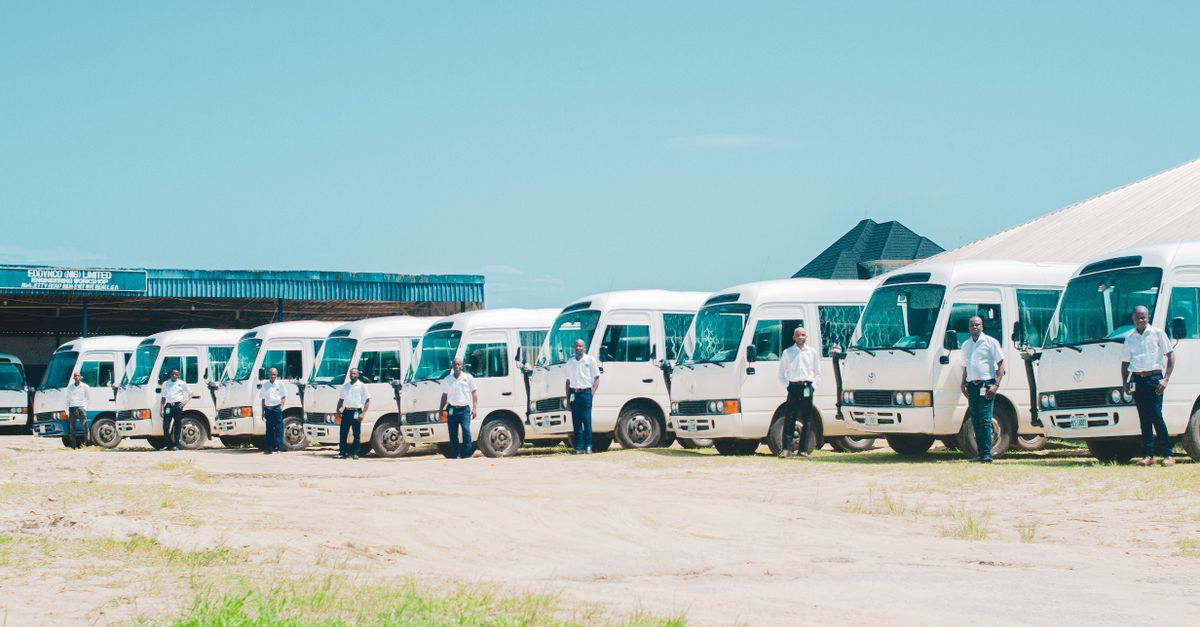
Drive45’s September 2026 guaranteed facility shows that operating quality may not remove market-level lending risk. Photo: Abasiakan / Pexels, Pexels licence (free commercial use).
This is the regional difference founders should not ignore. Strong unit economics and no default history can be necessary but still insufficient. Watu obtained debt-only funding without a reported guarantee. Drive45 needed credit enhancement despite its operating record. The comparison does not prove that Kenya is easy or Nigeria is impossible. It does show that lender requirements can change materially with the risk environment.
A company borrowing in a currency different from the one in which customers repay faces a particular exposure. If the repayment currency weakens, servicing the debt can become harder even if customer collections remain steady. The research brief flags currency risk as a factor in Drive45’s structure, but does not disclose the detailed facility terms. That gap should be a reminder to founders: the headline amount is only the start of the analysis.
GI Network's view: Watu’s US$7 million facility should make founders build a debt-readiness file before they need debt. The decisive asset is not a lender list. It is a verified portfolio record that lets a lender test collections, collateral and risk market by market.
What businesses should do by January 2027
First, separate capital needs by purpose. Identify which costs are linked to assets or receivables with a repeatable repayment record, and which costs are still experimental. Do not attempt to finance uncertainty with a facility designed for predictable collections.
Second, build an internal portfolio pack. It should let an external party trace loans from origination through repayment and, where applicable, through asset recovery. The research does not prescribe a standard reporting template, but Watu’s transaction makes the principle plain: lenders need evidence, not a broad statement that collections are healthy.
Third, document the assets that support each loan. Watu’s financed motorcycles and smartphones were central to the asset-backed case. Spiro’s fleet and battery infrastructure played the same role. If assets cannot be identified, valued or recovered in a practical way, a specialist lender may see less protection.
Fourth, map country risks separately. A multi-market company should not assume a strong record in one market removes currency or political risk in another. Drive45’s guarantee shows why a lender may require additional protection. Businesses should assess early whether a guarantee could be needed, rather than discovering that only after negotiating a facility.
Finally, avoid treating debt as a replacement for all future equity. AHL’s published 12% to 14% interest range and two-to-five-year repayment horizon show that debt creates a real obligation. A covenant, meaning a rule in the loan agreement the borrower must follow, can also limit operating freedom. Exact Watu covenants are not disclosed in the brief, but founders should expect lenders to seek controls where capital is tied to portfolio performance.
What investors should do by January 2027
Investors should ask management to produce a clear capital map: what equity will fund, what debt could fund later, and what data would unlock it. This can reduce avoidable dilution when a loan book becomes demonstrably financeable.
They should also test whether reported growth is collection-led or merely origination-led. Watu’s more than seven million originated loans are meaningful because the AHL facility was supported by an established asset-backed model and consistent repayment, not because the number is large in isolation. A rapidly expanding loan book without proven discipline is not automatically an investable debt story.
Next, investors should price country risk into the capital plan. Nigeria’s Drive45 shows why a company with credible operations might still need a guarantee. The relevant question is not whether management has “solved” risk. It is whether the proposed financing structure recognises who bears it.
Lastly, investors should consider the downside of refinancing too early. A facility that must be renewed before a business has stable funding alternatives can create pressure at precisely the wrong time. Our guide to refinancing risk with a mini-perm loan explains the wider principle: repayment capacity and the next source of capital need to be assessed together.
Where GI Network fits
GI Network can help a founder or investment committee turn a broad debt ambition into an investable financing brief. In this situation, that means separating assets and receivables that may support a facility from activities that still require equity; organising the repayment, collections and collateral evidence a lender will review; and mapping potential structures such as direct debt or a guaranteed facility against country-level currency risk. The work is educational and transaction-specific: it helps decision-makers understand what evidence a specialist lender is likely to require before entering a capital process.
What to watch next
Three signals over the next 90 days will show whether Watu is a one-off scale advantage or part of a wider market opening.
- By 31 October 2026: any further disclosure from Watu or AHL on the US$7 million facility’s permitted uses, repayment period, pricing, security or operating markets. Greater detail would show how closely it fits AHL’s published product.
- By 30 November 2026: new debt or guarantee-backed facilities for African asset-finance fintechs. A run of smaller transactions would matter more than one large announcement.
- By 31 December 2026: evidence that debt’s 57% share of African startup funding in Q1 2026 has held or moved lower. A reversal would temper the claim that the shift is structural.
- By 31 December 2026: any announced credit enhancement for operators in higher-risk markets, particularly structures that explicitly address currency risk. This would reinforce the Drive45 lesson that debt availability differs by market.
- By 10 January 2027: whether fintech and e-mobility operators continue to combine equity with portfolio debt, as Spiro did between late 2025 and mid-2026. That would confirm that the practical model is capital stacking, not an equity-versus-debt choice.
Watu has not made debt a universal answer for African fintech. It has made the standard clearer. Build a portfolio a lender can independently understand, control and recover against, and non-dilutive growth capital becomes a realistic option. Until then, equity remains the capital designed to carry uncertainty.
How do I build a repayment history clean enough for a bank or DFI to lend against?
Build consistent loan-level data, clear records of financed assets, repeatable collections controls and verifiable evidence that borrowers repay. A lender must be able to review how the portfolio performs, including under stress, rather than rely on growth claims alone. For asset-finance businesses, recoverable assets can strengthen the case, but disciplined repayment and collections records remain central.
Would a bank lend against my collections data today, and if not, what would it take to get there in twelve months?
A lender is more likely to lend when collections data shows predictable repayment, controlled losses and reporting that can withstand external review. If the data is not ready today, the next 12 months should focus on consistent loan-level reporting, documented asset records, repeatable collections processes and evidence that distinguishes genuine portfolio growth from arrears and losses. Strong operations may still require guarantees where currency or political risk is high.
For those who've raised pre-seed for Africa-focused fintech: how much traction did you actually have? Was it just an idea and a deck, or did investors expect live users, revenue, or partnerships locked in?
For portfolio debt, an idea and deck are not enough. The relevant traction is live lending activity, observable collections, a repayment record and, where applicable, assets that can be recovered. User numbers or partnership announcements alone do not provide the same evidence. Watu’s debt facility followed years of operations, more than seven million originated loans and an earlier financing relationship with its lender.
How do lenders price risk without traditional collateral?
The cases in the article suggest lenders seek other concrete protections rather than accepting a growth narrative in place of security. Watu and Spiro had physical assets that could support lending, including motorcycles, smartphones, electric fleets and battery-swap infrastructure. Drive45’s debt facility also used a credit guarantee to address currency and political risk. Verified collections and repayment performance help lenders assess the remaining portfolio risk.
What metrics should lenders track closely?
Lenders should closely track repayment behaviour, collections performance, arrears, write-offs, recovery rates and the recoverable value of financed assets. They also need loan-level data that separates portfolio growth from losses. The article does not report Watu’s specific arrears, write-offs or recovery rates, but identifies these measures as the kind of evidence a serious debt underwriting process should surface.
- Watu secures US$7 million debt facility from AHL Venture Partners · Publicnow · 10 September 2026
- AHL Working Capital Product · AHL Venture Partners · July 2025
- Watu receives US$5 million receivables financing facility for Uganda expansion · AHL Venture Partners · December 2022
- African startup debt versus equity shift in Q1 2026 · Algeria Tech · Q1 2026
- The African Tech Startups Funding Report 2024 · Disrupt Africa · 2025
- African e-mobility and DFI financing trends · Charged Africa · 2026
- Spiro financing coverage · Associated Press · mid-2026
- Guaranteed debt, a R50m bond and new fintech credit · Fluxis Newsletter · September 2026
- AHL Venture Partners (via Public) / AHL Venture Partners Deepen Financing Partnership with Watu
- Spiro secures $50 million from Afreximbank, others to expand Africa battery-swapping network
- How DFI Debt Is Replacing Equity as Africa's EV Growth Engine | CHARGED Deep Signal
- Guaranteed debt, a R50M bond and $255M in new fintech credit
- Africa Startups Q1 2026: Debt Overtakes Equity First Time
- OVERVIEW # Equity funding remains dominant but
Raising capital? Open a capital file and let the advisory team assess your position.
Apply for Capital