
Mini-perm loans fund the awkward middle stage between construction and proven long-term cash flow. They work when an asset has a clear, funded route to becoming refinanceable. They become dangerous when completion is mistaken for permanent-financing eligibility.
- ·A mini-perm has a shorter legal maturity than its repayment schedule, leaving a balloon that must be refinanced, repaid or covered by a sale.
- ·Investors accept mini-perm risk because it can provide funding when long-term lenders will not yet lend, while protecting lenders with cash sweeps, margin increases and strict conversion tests.
- ·Completion, stabilisation and takeout eligibility are three different milestones.
- ·A soft mini-perm can be economically painful long before its final maturity because cash may be trapped and pricing may rise.
- ·For property, future lenders look for stable occupancy, cash flow and value. For infrastructure, they look for operating evidence and credible contracted revenue.
- ·The sensible time to prepare a refinancing case is before signing the mini-perm, not in its final year.
In Bahrain, the sponsors of Al Dur IWPP had a loan that was designed to become more uncomfortable with age.
Al Dur, a power and water project, secured financing in 2009 in what Project Finance Law described as the Middle East project-finance market’s first mini-perm. The debt ran for eight years. Yet it repaid principal as if it had twenty. That left roughly 80% of the original balance still outstanding at the end.
The sponsors were meant to refinance by year five. Miss that target and the interest margin rose by 50 basis points. Every dollar of project cash was swept to repay debt rather than paid to the owners. Miss the final maturity and it became a default.
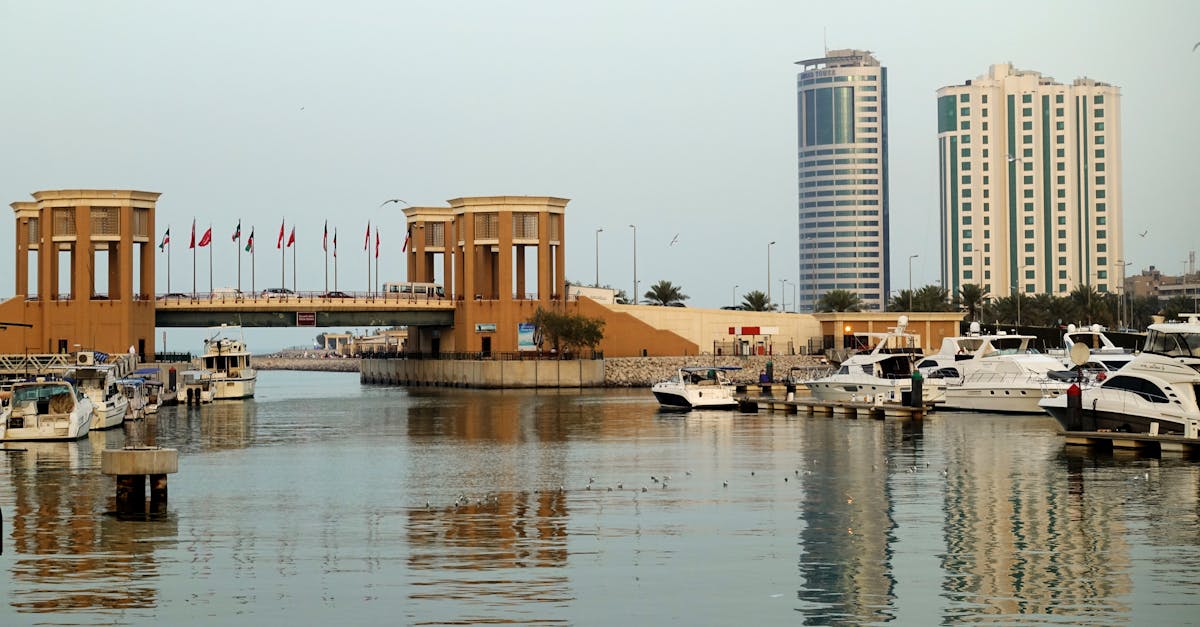
Al Dur shows how a supposedly soft maturity can impose severe refinancing pressure years before final default. Photo: Frans van Heerden / Pexels, Pexels licence (free commercial use).
That is the real story of a mini-perm. Not a clever name for a temporary loan. A countdown clock attached to an unfinished proof.
Why would sensible investors agree to that?
The bargain made after the crisis
At first glance, the answer seems obvious: nobody wants refinancing uncertainty. But Al Dur was financed after the global financial crisis, when bank liquidity mattered. The sponsors accepted a future refinancing obligation because five-year certainty of long-term debt was not the only thing in short supply. Immediate funding was valuable too.
This is where most people stop looking. They see the short maturity and assume the lender is simply taking more risk.
The opposite is often true.
The lender is willing to finance an asset before it has accumulated a long operating record, but it does not agree to wait indefinitely. It lends through a transition, then builds mechanisms that force the owners to solve the next stage. Higher pricing, blocked distributions and cash sweeps are not administrative clutter. They are the lender’s way of saying: prove this asset can stand on its own.
A mini-perm is therefore a maturity structure, not one universal product. It can fund a newly built apartment building, a floating production vessel or a renewable-energy project. Its legal term may be two years or eight. It may be limited-recourse, non-recourse or supported by guarantees.
What unites these deals is simpler. The payments are often calculated over 25 or 30 years, but the loan ends far earlier. The gap creates a balloon, the large unpaid balance due at maturity.
Someone else has to repay it.
Usually that means a new lender, a buyer, a bond issue or fresh equity.
Finishing the building is not enough
CW Broadway JV discovered how many hurdles can fit between construction and financing certainty.
In November 2019, PNC Bank agreed a $44.625 million construction and mini-perm loan for CW Broadway JV in the United States. The loan did not automatically become mini-perm debt because the building was complete. Before conversion, the borrower needed lien-free completion, a certificate of occupancy, no default, compliant guarantor finances, a maximum 60% loan-to-value ratio and at least 1.25x debt service coverage.
The mini-perm then lasted only 12 months, with one conditional 12-month extension. Each conversion or extension cost 0.25%. If the project later fell below the required debt-service coverage, excess cash could be swept until it passed two consecutive tests.

CW Broadway JV shows that completion must still clear leverage, cash-flow and guarantor tests before conversion. Photo: Marije Kouyzer / Pexels, Pexels licence (free commercial use).
Imagine you have built the asset. The doors open. The hard hats are gone. Yet the money is still conditional.
That is because completion, stabilisation and takeout eligibility are different things. Completion means the asset exists. Stabilisation means the income has become dependable. Takeout eligibility means a new lender believes the income, value and remaining debt fit its own rules.
Those rules can be surprisingly concrete. Fannie Mae’s multifamily guide generally points to around 90% physical occupancy sustained for 90 days for permanent financing. Freddie Mac’s small-balance guidance illustrates why cash flow matters too: permanent lenders commonly look for debt-service coverage of roughly 1.20x to 1.30x, while a lender funding an earlier transition may accept closer to 1.00x.
Debt-service coverage sounds technical, but it is just a household-budget question. Is there enough income to pay the debt with room to spare? At 1.25x, there is £1.25 of cash flow for every £1 owed in debt payments.
The SEC-filed CW Broadway agreement puts the lesson in black and white: even the initial lender wanted economics that resembled a future lender’s test. The building itself was never the whole collateral story.
GI Network's view: A mini-perm maturity is not the date to start a refinancing process. It is the deadline by which the asset must already look acceptable to the next lender.
Why a short loan can still make sense
The case for mini-perm debt is strongest when time changes the asset in a way that evidence can prove.
ReNew and Mitsui used approximately $985 million to $1 billion of five-year debt from 12 international banks for ReNew RTC, a 1.3GW wind, solar and battery project in India. The project had a 25-year power-purchase agreement with SECI, the state-owned counterparty.
Five-year debt against a 25-year contract may look mismatched. It is. Deliberately so.
The banks did not need to lend for the entire contract period on day one if the early years could establish operating performance and demonstrate the quality of the contracted cash flows. The power-purchase agreement gave the project something a newly completed office block may not have: a long runway of agreed revenue with a government-linked offtaker.

ReNew RTC demonstrates how long contracted revenue can support short initial debt while operations become proven. Photo: Hoan Ngọc / Pexels, Pexels licence (free commercial use).
That does not erase refinancing risk. It changes the evidence available when refinancing comes around.
For a developer seeking capital for a solar project, this distinction matters. Equipment is not the investment case. The investment case is whether the contracts, operations and cash receipts will satisfy a future capital provider.
Put Al Dur, CW Broadway and ReNew side by side and a pattern appears that none of the deals says quite so plainly: mini-perm lenders are not underwriting a finished asset. They are underwriting a transformation.
At Al Dur, the transformation was from post-crisis bank financing to a refinanceable operating project. At CW Broadway, it was from construction to stable property cash flow. At ReNew, it was from a contracted project on paper to a demonstrated operating business.
The investor accepts the uncertainty because it is controlled uncertainty. The borrower gets funding earlier than a permanent lender may offer. The lender gets a shorter exposure, protective covenants and a path to accelerate repayment if the transition goes badly. The owners retain upside, but cannot simply collect it while the project misses its refinancing target.
The clause nobody calls a default
A hard mini-perm is blunt. Failure to refinance by the final date is an event of default.
A soft mini-perm sounds gentler. It is often only gentler at the beginning.
World Bank guidance describes structures in which cash sweeps rise through 25%, 50% and 75%. Al Dur went further after year five: a 100% cash sweep and higher margin. The project might technically remain alive, but its owners lose access to the cash they expected to receive.
Here is the twist: a borrower can avoid legal default and still lose the economic point of owning the asset.
That is why experienced investors do not ask only, “When does the loan mature?” They ask what happens in every year before maturity. Is there an extension? What does it cost? Does the lender trap cash? Can distributions continue? Does the sponsor need to inject money if value falls?
A borrower with weak liquidity may not survive a soft structure’s pressure. An established sponsor with several funding channels may use it well, because it can refinance early if conditions are favourable and endure a delay if they are not.
Contracts can travel where tenant rolls cannot
In Spain, Grenergy arranged a different version of the same bargain.
In July 2026, Grenergy disclosed €100 million of non-recourse senior financing from Santander and SMBC for Oviedo BESS, a 154MW/618MWh battery project. The financing was structured as an eight-year mini-perm. The project had a ten-year tolling agreement and was expected to begin operations in the first half of 2027.

Oviedo BESS shows why contracted tolling revenue can matter as much as physical completion for a new asset class. Photo: David Vives / Pexels, Pexels licence (free commercial use).
A battery is not an apartment building. It cannot show occupancy. But it can show contracted revenue.
That is especially important in an emerging asset class, where a lender may be less confident about merchant revenues, meaning income exposed to changing market prices. The tolling agreement gives the future financing case something firmer to examine than a forecast.
Brazil offers another useful contrast. In August 2021, Yinson and Sumitomo raised $670 million of five-year limited-recourse mini-perm financing for FPSO Anna Nery, the floating production, storage and offloading vessel being completed for Petrobras. The financing refinanced a $400 million bridge and supported completion of the vessel.

FPSO Anna Nery illustrates mini-perm financing used to refinance bridge debt and support completion of a Petrobras-linked vessel. Photo: Dan Lynch / Pexels, Pexels licence (free commercial use).
The point is not that every operating contract guarantees a takeout. It does not. The point is that contracts and operating history can turn a construction proposition into a cash-flow proposition, which is exactly what a later lender wants to see.
In Southern Africa, the problem can be even more basic: long-term local debt may not be available in sufficient quantity. In April 2026, Dutch development bank FMO proposed a $42.5 million committed facility, plus a prospective $42.5 million facility, to refinance Solarcentury Power assets in Namibia and Zambia and finance a 113MW Botswana project through a mini-perm structure.
There, the mini-perm is not merely a bridge through lease-up or commissioning. It is also a response to scarce long-dated capital.
When the logic breaks
The structure fails when the supposed transition does not create stronger proof.
A building with uncertain demand may not reach stable occupancy. A project with weak contracts may not persuade a replacement lender. A sponsor that cannot meet extension fees, mandatory repayments or a cash sweep may be forced into a sale at precisely the wrong time.
Nor does a long contract automatically settle everything. Future lenders still care about operating performance, the remaining debt balance and their own appetite for the sector.
The uncomfortable implication is that a mini-perm cannot solve an asset’s underlying weakness. It can only buy time for a genuine improvement to become visible.
What owners should build before they borrow
Founders, developers and asset owners should begin with the exit evidence, not the opening rate.
First, identify the next lender’s likely tests. For property, that may mean occupancy, cash flow, valuation and sponsor support. For infrastructure, it may mean operating history, contract quality and the credibility of the revenue counterparty.
Second, map the timing honestly. How long will it take to reach those tests? How much debt will remain by then? What happens if operations or lease-up take longer than planned?
Third, model the ugly version. Lower valuation. Slower income. Higher refinancing cost. Restricted distributions. If the deal only works under the optimistic case, it is not a financing plan. It is a hope with legal documents.
The same discipline belongs in the wider question of how much to raise. Raise enough to fund the proof that the next capital provider needs, including the possibility that proof takes longer than expected.
What investors see first
Investors should treat a mini-perm as a future capital event hiding inside today’s debt package.
Ask four questions. What will be different about this asset before maturity? Who is expected to lend or buy next? How much will that party plausibly provide? And what happens if the answer is less than the balloon?
The first-time founder often sees lower initial pricing and more immediate funding. The experienced investor sees the maturity wall, the extension provisions and the potential equity call if values or cash flows disappoint.
GI Network would approach a mini-perm mandate by testing the proposed maturity against the asset’s actual route to proof. That means identifying the operational milestones a future lender will require, modelling downside refinancing capacity, examining conversion and cash-sweep provisions, and preparing materials around the specific replacement debt or equity sources that fit the asset once it has de-risked. The aim is to expose a weak exit before capital is drawn, when it can still be redesigned.
The proof-before-payoff test
Before signing a mini-perm, use the Proof-Before-Payoff Test:
- 1.Proof: What measurable evidence will the asset produce before maturity: occupancy, operating history or contracted cash flow?
- 2.Provider: Which realistic next lender or buyer will value that evidence?
- 3.Payoff: Will that party provide enough to clear the balloon, after allowing for a weaker valuation or slower ramp-up?
- 4.Pressure: What happens to cash, pricing and ownership control if refinancing is late?
If those four answers are clear, a mini-perm can fund a sensible transition. If they are vague, the loan is not bridging a gap. It is moving the gap into the future.
What is the difference between mini-perm and permanent financing?
A mini-perm is shorter-term financing that carries an asset through construction, lease-up or early operations, while permanent financing is intended to last much longer once income is stable. Mini-perms often amortize over 25 to 30 years but mature in two to eight years, leaving a large balloon balance that must be refinanced, repaid through a sale or covered by other capital.
When should I use a mini-perm?
A mini-perm can suit an asset that needs time to become financeable on permanent-loan terms. Typical situations include a newly completed property still leasing up, a repositioning project, or an infrastructure asset building an operating record. It works best when there is a credible path to stronger cash flow, valuation and takeout eligibility before the loan matures.
Are mini-perms recourse or non-recourse?
Mini-perms can be recourse, limited-recourse or non-recourse. Recourse is not determined by the mini-perm label because a mini-perm is a maturity structure, not a single standard loan product. The treatment depends on the specific financing agreement, including any sponsor guarantees, completion support, liquidity obligations and default provisions.
What is the difference between a hard and a soft mini-perm?
A hard mini-perm makes failure to refinance by the final maturity date an event of default. A soft mini-perm may avoid an immediate default but becomes more restrictive over time, often through higher interest margins, cash sweeps and blocked owner distributions. In a soft structure, the borrower may remain legally current while losing access to project cash flow.
What happens if the loan is not refinanced by maturity?
The outcome depends on the loan terms. In a hard mini-perm, failure to refinance at final maturity is usually a default. In a soft mini-perm, pressure can begin earlier through escalating cash sweeps, margin increases and restrictions on distributions. The unpaid balloon balance still needs a takeout, such as refinancing, a sale, bond issuance or new equity.
- Guidance on PPP Contractual Provisions · World Bank · 2017
- CW Broadway JV construction and mini-perm loan agreement · SEC · November 2019
- Project bonds and mini-perms: a new era in the Middle East · Project Finance Law · November 2012
- Multifamily Selling and Servicing Guide · Fannie Mae
- Small Balance Loan Term Sheet · Freddie Mac
- Largest single project financing facility in India for round-the-clock renewable energy · Crédit Agricole CIB
- Yinson and Sumitomo secure USD670 million mini-perm financing for FPSO Anna Nery · Yinson Production · August 2021
- Grenergy disclosure on Oviedo BESS financing · CNMV · July 2026
- Solarcentury Power project detail · FMO · April 2026
- Mini perm refinancing – In markets where it is not possible (or desirable) to obtain long term financing, the Private Partner may put in place what is sometimes known as a “mini perm” financing. The loan will have a short tenor (e.g. five or seven years), and there is an incentive on the Private Partner and its Shareholders to refinance because the loan terms may provide that the Lenders will sweep all available cash (after reserve account funding) if no refinancing has occurred by the relevant maturity date (and the Lenders may require gradually increasing cost sweeps (e.g. 25%, 50%, 75%) in the years prior to maturity), or (in the case of a “hard” mini perm) that there will be an event of default⁴⁴. The market standard position in Australia, for example, is to put in place five to seven-year debt funding, with assumed refinancings every five years thorough the life of the PPP Project. Given the nature of this financing and that replacement will be a necessity envisaged at the start of the PPP Contract, it will be in both Parties’ interests to facilitate a refinancing on acceptable terms and it is unlikely to be driven by or to deliver any significant additional financial benefit.
- EX-99.1
- Mini Perm Financing | Glossary | Practical Law
- Occupancy | Fannie Mae Multifamily Guide
- small balance loan term sheet
- www.sec.gov
- Project Bonds and Mini-Perms: A New Era in the Middle East | Norton Rose Fulbright - November 2012
- Largest single project financing facility in India to power its first round-the-clock renewable energy programme | Crédit Agricole CIB
Raising capital? Open a capital file and let the advisory team assess your position.
Apply for Capital